

RedotPay: Crypto Card & Pay
4.4

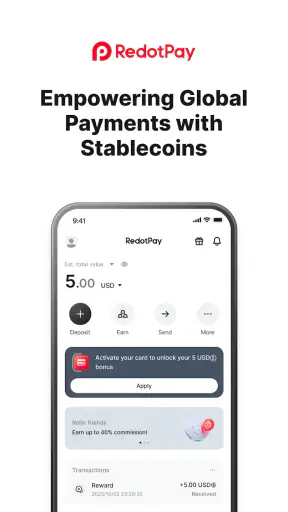
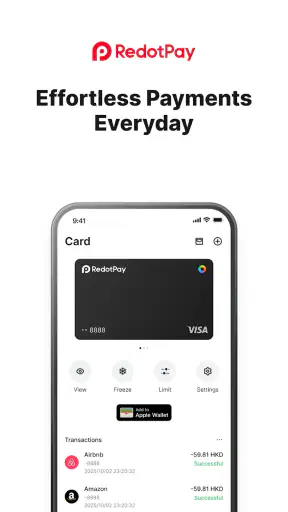
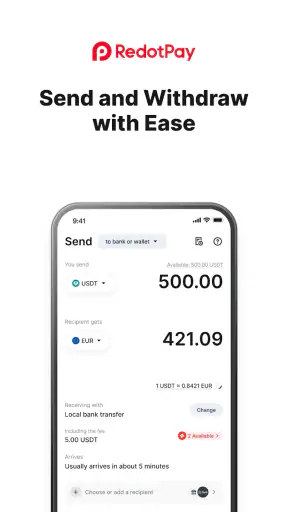
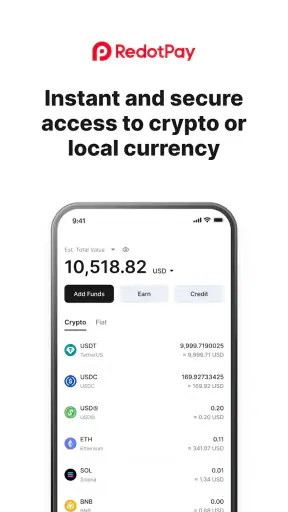
I approached RedotPay: Crypto Card & Pay as a practical finance app rather than as another cryptocurrency dashboard. Its central appeal is straightforward: it is designed to help people use digital assets for spending, while also bringing wallet tasks such as earning, swapping, and sending into the same place. That makes it interesting for someone who wants crypto to fit into everyday payments instead of remaining entirely inside an exchange account.
My overall impression is positive but conditional. The app is free to install, its audience rating is Everyone, and its presence on mobile is substantial, with more than five million installs and an average score of 4.4 from roughly seventy-three thousand ratings. Those figures suggest that it has reached well beyond a small group of early crypto enthusiasts. Still, popularity does not remove the need to understand how you plan to use it, because a crypto payment tool can be convenient for one person and unnecessarily complicated for another.
How RedotPay fits into everyday crypto spending
Red Dot Technology Limited developed RedotPay as a finance app built around the idea of spending crypto like ordinary money. In practice, that positioning matters because many wallet apps are mainly concerned with holding assets, while many exchanges focus on buying and selling. RedotPay sits closer to the payment side of the experience, combining a wallet with tools for swapping and sending and presenting the card as part of the same spending journey.
I find that combination more useful than a wallet that only displays balances. If I am managing digital assets for a real purchase, I want to think about the complete path: where the funds are held, whether I need to exchange them, how I send them, and how I actually pay. Keeping those activities in one finance app can reduce the need to move between several services, which is especially helpful when I am checking a transaction on a phone.
That convenience should not be confused with simplicity in every situation. Crypto payments still require attention to the asset being used, the destination, and the transaction details. A clean interface can make the process easier to follow, but it cannot make an unsuitable asset or an incorrect transfer harmless. My advice is to treat the app as a spending tool that rewards careful habits, not as a shortcut around the basic responsibilities of using cryptocurrency.
The cost question is refreshingly simple at the starting line
RedotPay is free to download and use at the entry level. That is the clearest value point for a curious user: I can explore the app without paying an upfront purchase price. It also means the decision to try it is different from choosing a paid budgeting app or buying a premium finance tool before knowing whether its workflow suits me.
Free access does not automatically mean every possible activity has no cost. With a crypto card and wallet service, the practical value depends on the terms attached to particular transactions, card use, conversion, transfers, or other account actions. I would therefore avoid treating the word “free” as a promise that every movement of money is costless. Before using it for a meaningful balance, I would inspect the in-app details for the exact action I intend to perform.
This distinction is important because the app’s value is not the same for someone merely exploring and someone using it as a regular payment method. For the first person, free access makes experimentation easier. For the second, the relevant question is whether the complete transaction experience remains worthwhile after any applicable charges, conversion differences, or practical restrictions. The download price answers only the first part of that decision.
What I would use it for first
My first use would be a small, controlled payment workflow rather than moving a large balance immediately. I would set up the wallet, review the available actions, and learn how the app presents sending, swapping, and spending before relying on it for an important purchase. That approach gives me a chance to understand the confirmation screens and the relationship between the wallet side and the card side.
A realistic example would be a traveler who keeps some crypto for spending while abroad. Instead of opening a separate wallet to check funds, an exchange to convert assets, and another payment service to complete a purchase, that person could use RedotPay as the central mobile tool. The benefit is not just fewer icons on the phone. It is the ability to follow the money through a single workflow and make a quicker decision about whether to swap, send, or pay.
There is a useful trade-off here. Consolidation can make a routine action less tiring, but it also makes the app more important to the user’s overall setup. If the individual prefers to separate long-term holdings from spending funds, keeping everything together may feel uncomfortable. I would use a dedicated spending balance rather than treating a payment-focused app as the only place for assets I intend to hold for a long time.
Swapping and sending require different kinds of attention
The presence of swap and send tools may look like a minor convenience, but they serve different purposes. Swapping is about changing one asset into another within the user’s financial plan. Sending is about moving funds to a destination. I would never treat those buttons as interchangeable simply because they appear near each other in the same app.
For a swap, I would check the asset pair, the amount, and the final result shown before confirming. For a send, I would concentrate on the recipient details and the network or destination information presented by the app. A payment-oriented interface can encourage speed, especially when I am standing at a checkout or trying to solve a problem while traveling. My practical tip is to slow down precisely when the app makes the action feel easiest.
Another useful habit is to separate “available to spend” from “available in the wallet.” A balance can look healthy while still being unsuitable for a particular payment or transfer. I would decide in advance how much I am comfortable using for everyday purchases and leave the rest outside that active spending plan. This is a personal workflow choice, but it helps prevent an ordinary card purchase from becoming an impulsive portfolio decision.
The card concept is strongest for people who want a bridge
The card is the feature that gives the app a clearer identity than a standard wallet. A wallet is useful when I want to hold or move crypto; a card is useful when I want to bring that value into a familiar payment context. That bridge is the main reason I would recommend investigating RedotPay instead of installing another wallet with no spending focus.
However, the bridge also creates expectations that need to be managed. A crypto card is not necessarily identical to a traditional bank card in how funds are sourced, converted, settled, or supported. I would read the app’s current explanations carefully and test the experience with a modest amount before making it my only payment option. If a person needs predictable conventional banking features above all else, a regular debit card may remain the better everyday choice.
RedotPay makes more sense when the user already has a reason to hold crypto and wants a more direct route from that balance to spending. It makes less sense when the user does not use digital assets at all. In that case, adding a crypto layer can create extra decisions without solving a real problem that a normal bank or card app does not already handle.
Where the free model delivers genuine value
The strongest value is the chance to explore a crypto spending workflow without an upfront purchase. I can evaluate whether the wallet, swap, send, and card-oriented approach fits my habits before committing to it as part of my financial routine. That is especially helpful for people who dislike paying for an app before they understand its usefulness.
The second value point is concentration. Having payment-related crypto actions in one app can save time and reduce context switching. I would particularly appreciate that when checking a balance before a purchase, preparing funds for spending, or deciding whether a transfer is necessary. The app’s appeal is therefore less about a single spectacular tool and more about how its pieces support one another.
The third value point is accessibility. It runs on Android from version 7.0 onward, so it is not limited to only the newest phones. That broader device compatibility can matter to users who keep an older handset as a travel phone or who do not upgrade frequently. I would still judge the actual experience on my device, but the stated operating-system requirement makes the app approachable for a wider Android audience.
The current version is 3.13.2, which tells me that the product has continued through multiple iterations rather than remaining at an untouched launch build. I would not interpret a version number as a guarantee of flawless performance, but it is relevant when deciding whether the app appears actively maintained enough to deserve a trial. The release date of June 9, 2023, also places it as a relatively recent product rather than a long-established traditional banking application.
Important friction before making it a primary payment app
The first limitation is the learning curve created by combining crypto management with spending. A conventional card app usually asks me to think about a balance and a payment. RedotPay asks me to think about a wallet, digital assets, possible swaps, transfers, and card use. That broader scope is valuable for the right person, but it can feel like unnecessary mental overhead for someone who only wants to pay bills or buy groceries.
The second limitation is that crypto value can change, while everyday spending is usually planned in ordinary currency. Even when the app makes payment convenient, I still need to consider what I am giving up when I spend an asset. I would not use a volatile holding for routine purchases without understanding that trade-off. A normal bank account is often better for predictable budgeting because the spending balance is easier to interpret.
The third limitation is operational risk. Sending crypto requires precision, and a mistake can be more serious than entering the wrong amount in a simple shopping app. I would verify every destination and avoid rushing through a transfer on a poor connection or in a crowded checkout line. RedotPay can organize the process, but responsibility for the decision remains with me.
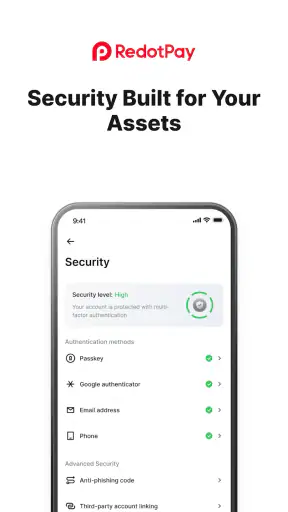
There is also a privacy and trust consideration that applies to any finance app handling payment activity. I would be comfortable testing it only after reviewing the permissions and account-security choices shown during setup. I would also keep recovery information protected and avoid using a shared device for sensitive actions. These are not reasons to reject the app automatically; they are reasons to treat it like a financial instrument rather than a casual utility.
Who is likely to get the most from it
I see the best fit in a few specific groups. The first is an existing crypto user who wants a practical spending route instead of leaving assets idle in a wallet or exchange. The second is a traveler who values having wallet and payment actions close together. The third is a technically comfortable user who is willing to check transaction details and learn the app’s flow rather than expecting every crypto action to behave like a bank transfer.
It can also suit someone comparing crypto payment options and wanting to begin without an upfront app purchase. The free starting point lowers the barrier to testing the interface, while the Everyone content rating keeps it broadly accessible from an age-classification perspective. I would still make financial decisions based on the user’s own situation, not on the age label alone.
I would skip it if I have no interest in cryptocurrency, if I need a conventional current-account replacement, or if I am uncomfortable handling asset swaps and transfers. I would also choose a simpler alternative if my only goal is expense tracking, bill reminders, or ordinary card budgeting. RedotPay is more specialized than those tools, and specialization is not automatically an advantage when the underlying need is basic.
How it compares with familiar alternatives
Compared with a standard bank card app, RedotPay offers a more direct relationship with crypto but may require more financial awareness. A bank app is usually the natural choice for salary payments, fixed bills, and predictable household budgeting. RedotPay is more compelling when the starting balance is digital assets and the desired endpoint is spending them.
Compared with a standalone crypto wallet, it is more payment-oriented. A pure wallet may be preferable for someone who prioritizes control over storage and transfers and does not want a card-centered experience. RedotPay is better aligned with someone who wants to connect holding, swapping, sending, and spending in one mobile environment.
Compared with a crypto exchange, its appeal is convenience at the point of use rather than a trading-first workspace. An exchange may be more suitable for users whose main activity is market analysis or active buying and selling. I would choose RedotPay when the question is “How can I use this balance?” rather than “How can I trade as efficiently as possible?”
That comparison also explains why I would not call it a universal replacement. It is a bridge product. Its success depends on whether I need the bridge between crypto and payments. If I do, the combination is meaningful. If I do not, the extra layer can make my finances harder to understand.
My practical setup and safety routine
If I were introducing a friend to the app, I would suggest starting with observation rather than immediate funding. Install it, examine the wallet and payment sections, and note how the app describes each action. Then I would use a small amount that is genuinely set aside for experimentation. This makes the first test educational instead of financially stressful.
I would keep a written record of what I intended to do before confirming a swap or transfer: the asset, amount, destination, and purpose. That simple note helps catch mistakes caused by tapping quickly or confusing one action with another. For regular spending, I would review the balance before leaving home and avoid making a last-second conversion decision at the checkout.
I would also maintain a backup payment method. Even if RedotPay works well in normal conditions, relying on one app and one card for travel or essential purchases is unnecessarily fragile. A conventional card or another prepared option gives me flexibility if I encounter an unexpected issue, a device problem, or a payment situation where crypto is simply not the right tool.
Finally, I would revisit the app’s current terms whenever my usage changes. Trying a free app with a small balance is one decision; using it for frequent international spending is another. The more often I use the card, swaps, or transfers, the more important it becomes to understand the applicable conditions instead of assuming that the initial trial experience tells me everything.
My verdict on value and whether to try it
RedotPay earns its place on my shortlist because the free entry point lets me test a focused idea: using crypto in a more payment-friendly way. Red Dot Technology Limited has brought wallet, swap, send, and card-related activity into a single finance app, and that combination can be genuinely useful for people who already live partly in the crypto world.
I would recommend trying it to a careful crypto user who wants a spending bridge and is prepared to learn the details. I would not recommend replacing a conventional bank card immediately, and I would not suggest it to someone who has no practical reason to use cryptocurrency. The app’s value comes from matching the right workflow, not from being free by itself.
My final advice is to judge it through a small, realistic test: explore the interface, prepare a limited spending balance, complete only an action you fully understand, and compare the experience with the bank or exchange tools you already use. If the unified workflow saves time without making your finances harder to follow, RedotPay may be a strong fit. If it adds more crypto decisions than your everyday life needs, skipping it is the more sensible choice.
In short, this is a specialized finance app with a clear purpose rather than a universal money manager. Its free access, broad Android compatibility, and strong user adoption make it easy to investigate, while its crypto-centered trade-offs demand care. The best reason to use it is not simply to hold crypto, but to connect a crypto balance with a deliberate, controlled spending routine.
4.4
1.27K Reviews
Pros
- Virtual and physical card options support different spending preferences.
- Real-time transaction notifications make it easier to monitor card activity.
- In-app crypto-to-fiat conversion simplifies payments at supported merchants.
- Card controls can help users manage security and spending settings.
- Useful for travelers seeking an alternative to traditional payment cards.
Cons
- Availability and features may vary depending on the user’s country.
- Crypto prices can change quickly before a transaction is completed.
- Fees may apply to conversions
- withdrawals
- or specific card transactions.
- Identity verification is required before accessing many important features.
- Not every merchant or ATM may accept the card or its payment network.


